PayOffPath
Available on Google PlayAndroid
Organize your debts, compare payoff strategies, and see how extra payments can change your debt-free timeline.
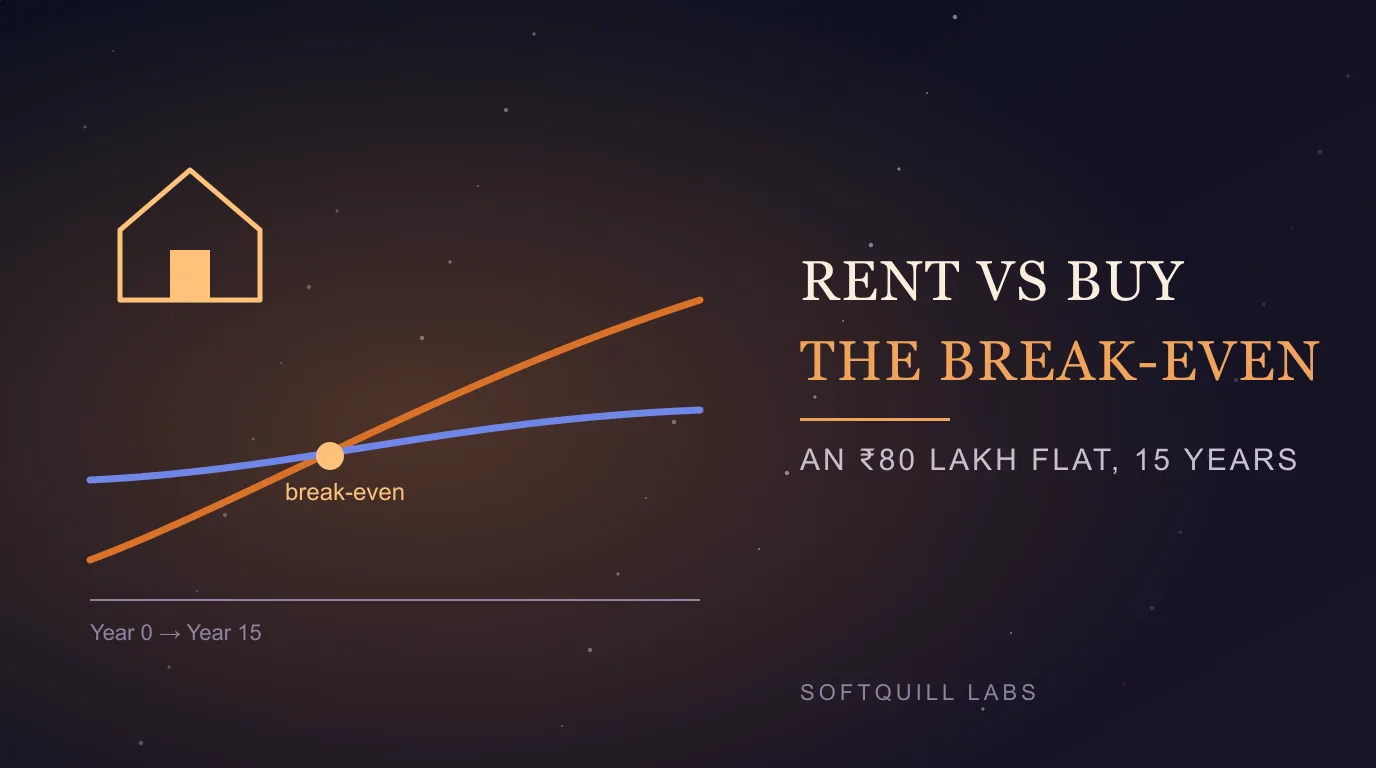
Instead of asking whether buying is 'better', ask what has to be true for it to win. For an ₹80 lakh flat, the answer is a specific annual price growth, and it depends on what you do with the money you did not spend.
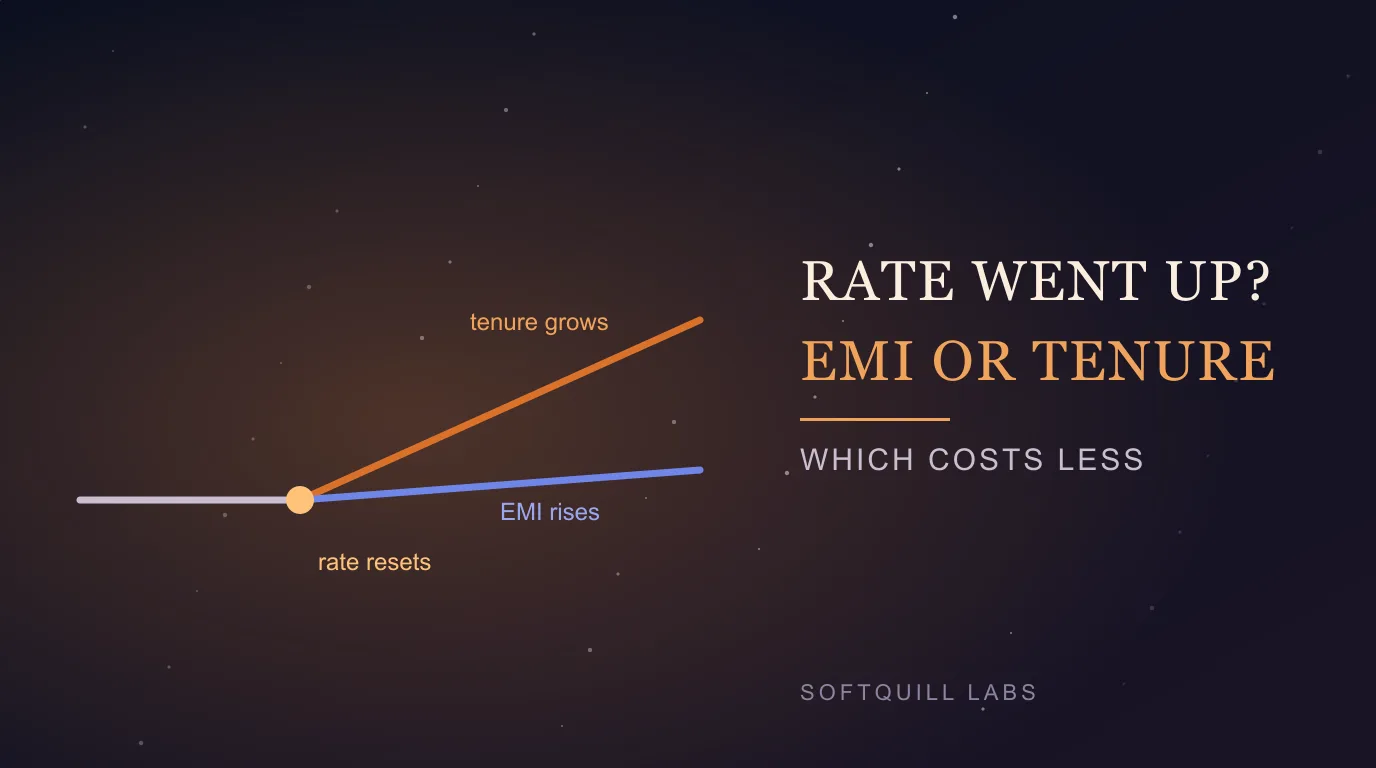
A 0.5% rate rise sounds small. Whether it lands on your EMI or on your tenure changes what it costs you by several lakhs.
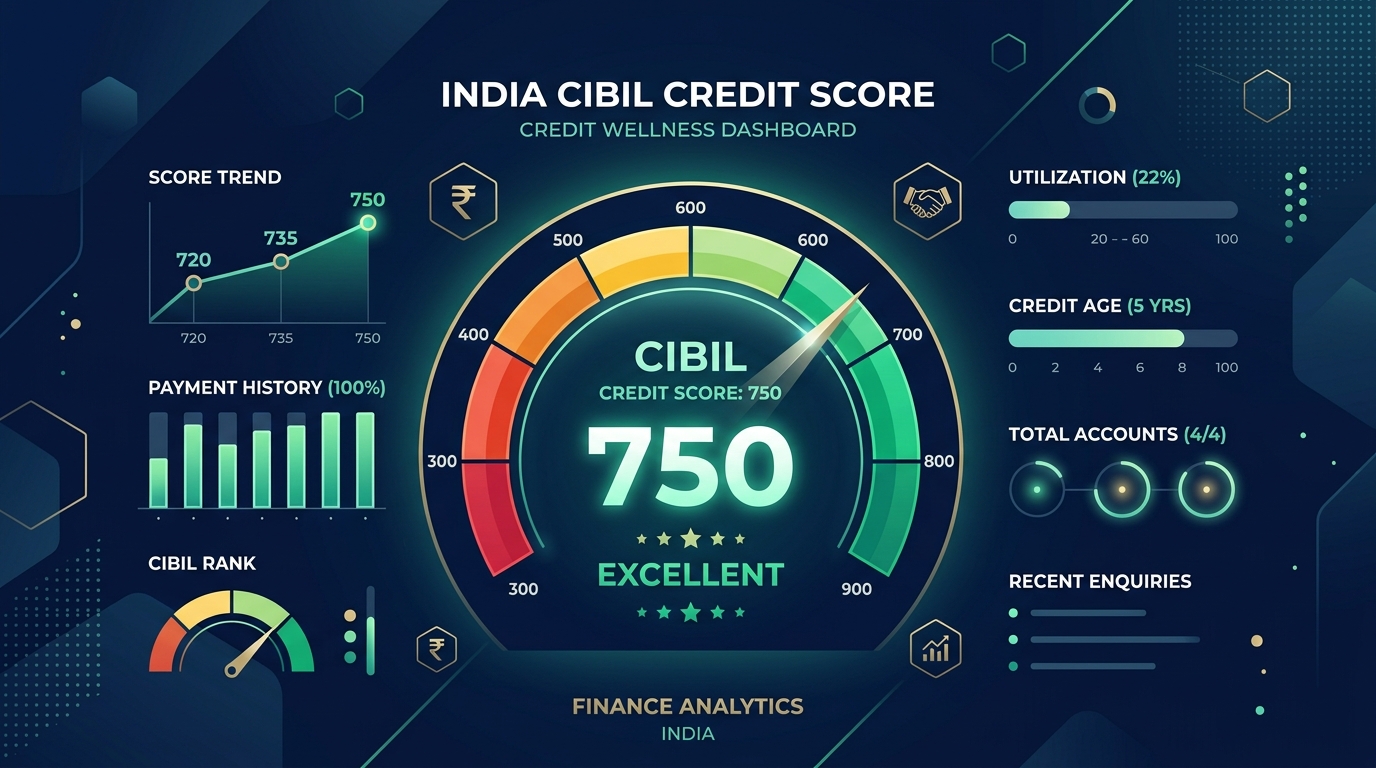
Your CIBIL score isn't random guesswork. It is a weighted mathematical algorithm calculated across five specific parameters. Here is exactly how it is computed, what score bands mean, and why 750 is the golden number for Indian borrowers.
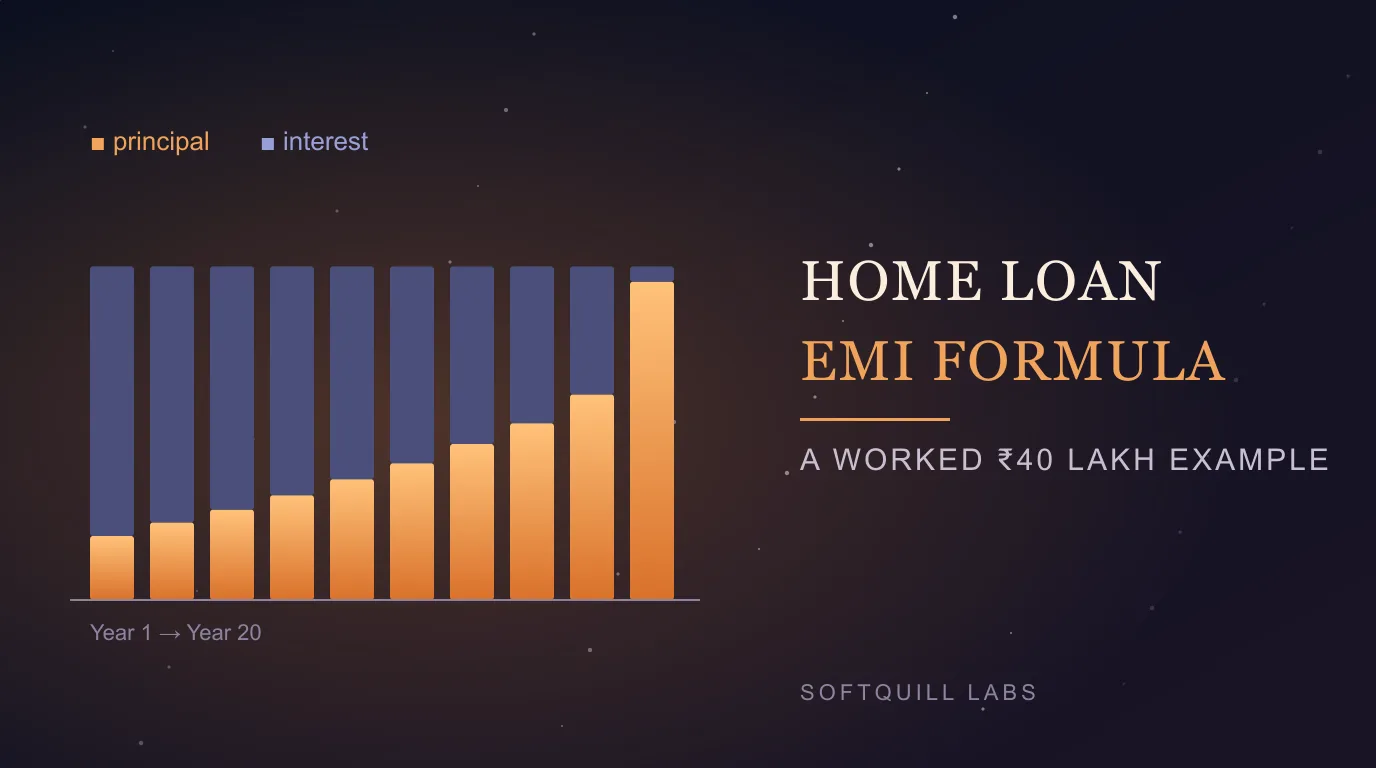
Your bank gives you one EMI number. This guide shows where it comes from, why most of the early payments are interest, and how a half-point change in rate moves the total by lakhs.
Learn how to become debt-free in India with seven practical steps to manage EMIs, repay credit cards, plan your budget, and avoid new borrowing.
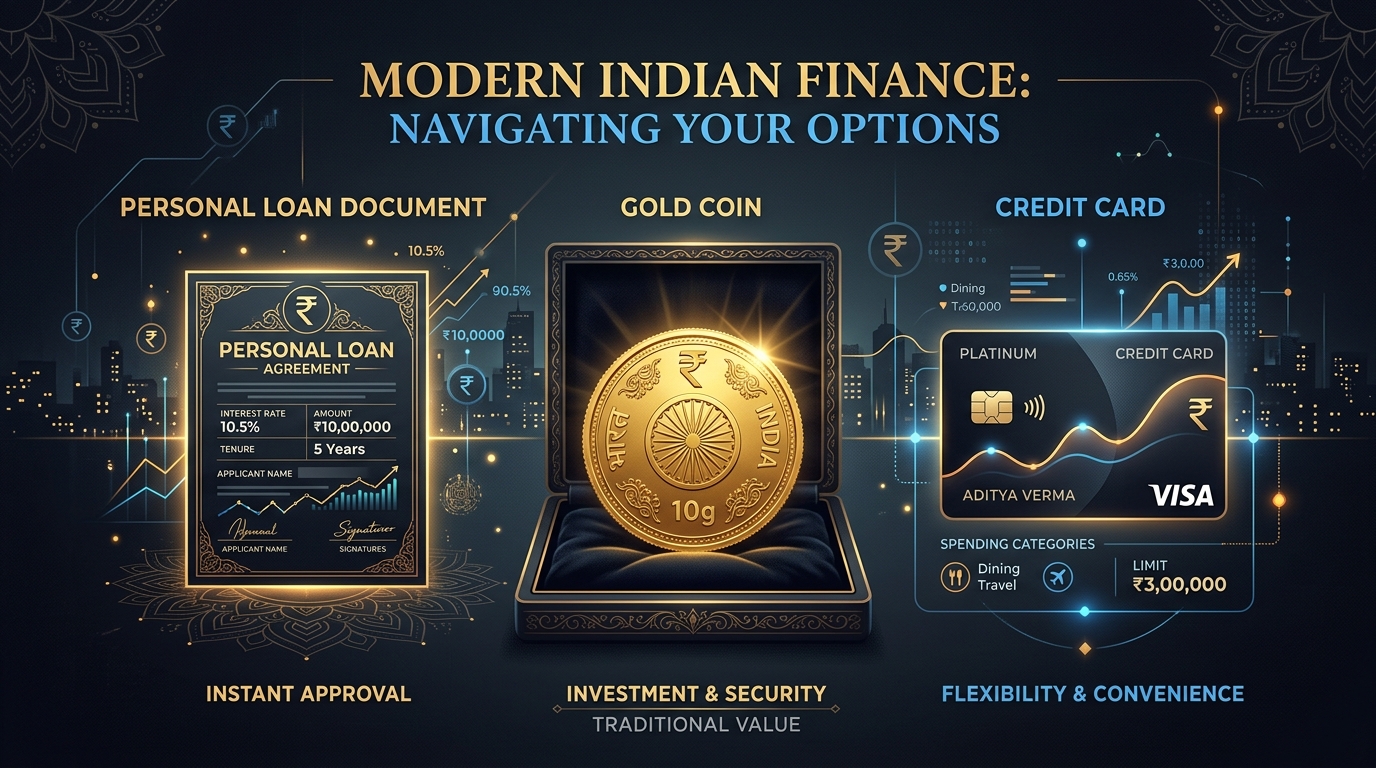
When you need ₹1 Lakh to ₹3 Lakhs urgently for medical bills, family weddings, or home repairs, Indian banks offer multiple instant options. Here is the honest comparison of which one costs the least.
Moving high-interest credit card debt to a 0% introductory card sounds like free money. But with balance transfer fees typically at 3% or 5%, here is how to calculate whether you come out ahead — and where to find true $0 transfer fee options.
With online banks offering 4.5% to 5.0% on savings accounts, many people wonder: should I hoard cash in a high-yield account, or aggressively pay off my loans? Here is the honest math.
Most people don't realize that in the first few years of a mortgage or auto loan, up to 70% of each payment goes directly to bank interest. Here is how adding a little extra changes everything.
When you buy a flat in Bengaluru, Mumbai, or Pune, taking a 20-year home loan feels normal. But did you know you might pay more in interest than the flat itself? Here is how small part-payments change everything.
Comparing the Debt Snowball vs Debt Avalanche method? Here is the exact mathematical difference, interest savings, and a worked $25,000 example with numbers you can check.
From sudden corporate layoffs to hospital emergencies not fully covered by insurance, an emergency fund is your financial shield. Here is how to calculate your number and where to keep it safely.
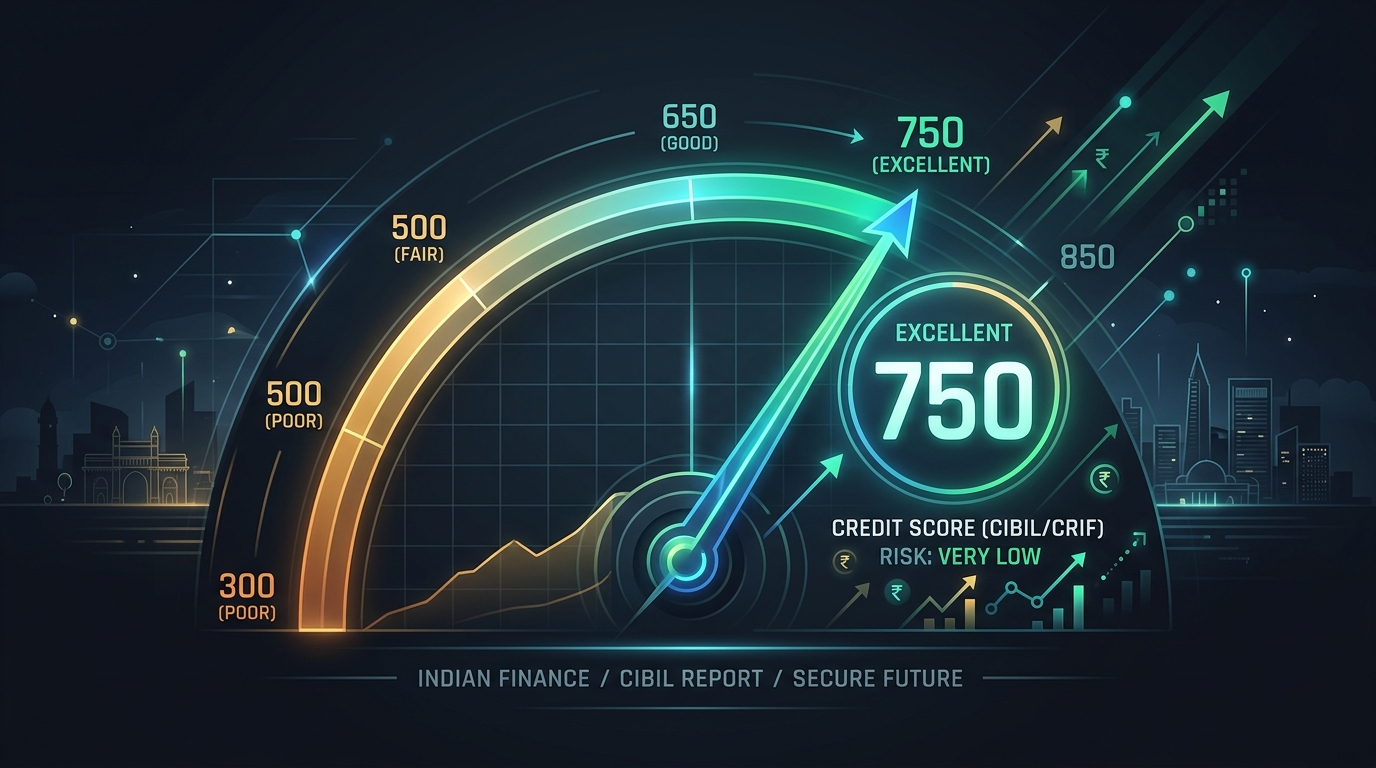
Whether your CIBIL score is sitting at 500 after a default, stuck at 600 from high card utilization, or sitting at a borderline 747, crossing 750+ is completely achievable. Here is the realistic month-by-month recovery roadmap.
When your monthly credit card statement arrives with a Total Due of ₹80,000, paying the ₹4,000 "Minimum Due" feels convenient. But here is the brutal truth of what banks don't highlight.
Do you pay your credit card in full every month, but your credit score still drops? You might be paying on the wrong day. Here is the simple timing trick that fixes it.
Organize your debts, compare payoff strategies, and see how extra payments can change your debt-free timeline.